Navigating Kigali's Mortgage Market as a Non-Resident
Returning to Rwanda to build or buy a home is a profound milestone. For many in the diaspora, securing a footprint in neighborhoods like Kibagabaga, Nyarutarama, or Kanombe represents both a financial investment and a deeply personal return to one's roots. However, navigating cross-border financing from thousands of miles away requires careful planning. Fortunately, a clear process removes the uncertainty associated with international property purchases.
Qualitative Comparison of Major Diaspora Mortgage Providers
✨
Ecobank Rwanda
High (USD, EUR, RWF)
Foreign Income AssessmentStandardized pan-African
Digital ProcessingModerate
✨
I&M Bank Rwanda
High (Multiple currencies)
Foreign Income AssessmentPremium tailored assessment
Digital ProcessingAdvanced
✨
KCB Bank Rwanda
Regional focus (USD, RWF)
Foreign Income AssessmentFlexible regional criteria
Digital ProcessingStandard
Rwanda's banking sector has recognized the economic power of its citizens living abroad. Institutions like Ecobank, I&M Bank, and KCB have developed specialized mortgage products to serve this exact demographic. Market data consistently shows that non-resident buyers prioritize flexible currency options and streamlined digital approvals when selecting a financial partner.
According to Rehani Soko property analytics, demand for residential units among diaspora buyers has steadily increased. Buyers are particularly interested in structured financing in foreign currencies like USD or EUR to mitigate exchange rate fluctuations against the Rwandan Franc (RWF). Furthermore, according to Rehani Soko occupancy data, diaspora-owned properties in prime Kigali areas maintain high tenant retention when rented out. When you decide to explore properties in Kigali, understanding how these banks evaluate foreign income is your first critical step.
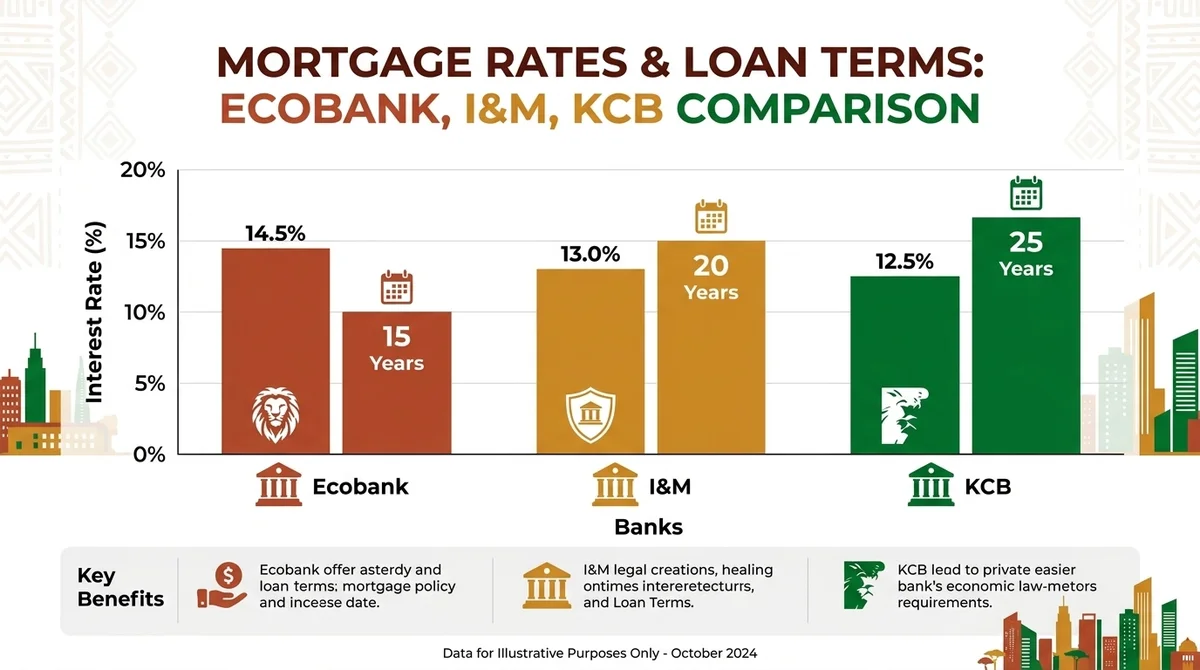
Each lender applies different criteria for Loan-to-Value (LTV) ratios, interest rate structures, and repayment tenors. To help you prepare, we have summarized the qualitative features of these major lenders based on Rehani Soko market intelligence.
Rates on the Rehani network · Kenya
Live Rehani network quotes for a Kenya apartment in KES.
Visual summary: The comic series below walks through the story and ideas in this article.
📖
Kigali Dreams, Diaspora Reality
Page 1 of 5
Before committing to a specific bank, it is essential to calculate your potential monthly obligations. Using a dedicated mortgage calculator allows you to model different scenarios based on your current country of residence and income profile. By comparing the structural benefits of Ecobank, I&M, and KCB, you can confidently select a financing path that aligns with your long-term vision for returning home to Rwanda.
Ecobank Rwanda: Pan-African Reach and Diaspora Account Perks
For Rwandans living abroad, financing a home from thousands of miles away often feels overwhelming. However, a clear process removes the uncertainty. Ecobank Rwanda stands out for its extensive pan-African network, which simplifies income verification for expatriates working across the continent or further abroad. Returning to your roots is a proud milestone, and securing the right financing ensures your transition home is seamless. According to Rehani Soko market intelligence, diaspora buyers using pan-African institutions often experience faster preliminary approvals because their foreign income is more easily verified through the bank's global branches.
Estimated Mortgage Setup Cost Breakdown in Rwanda
💰Valuation Fee
Typical Cost RangeVaries by lender
Payment TimingBefore loan approval
💰Arrangement Fee
Typical Cost RangeVaries by lender
Payment TimingUpon loan acceptance
💰Legal & Registration
Typical Cost RangeVaries by lender
Payment TimingDuring title transfer
💰Insurance (Life & Fire)
Typical Cost RangeVaries based on age and value
Payment TimingAnnual premium at closing
One of the main attractions of Ecobank is its dedicated diaspora account structure. When you are ready to secure properties in Kigali, having an integrated account allows you to manage your mortgage payments across multiple currencies. Rehani Soko data shows that cross-border transfer fees can add significant amounts to your total transaction costs if not managed correctly. Ecobank’s internal transfer systems help mitigate these hidden expenses, keeping your monthly obligations predictable. Transaction patterns confirm that buyers who align their currency earnings with their mortgage structure avoid severe exchange rate shocks.
Before committing to any financial product, it is essential to understand the initial setup costs associated with securing a mortgage in Rwanda. Market data consistently shows that preparing for these upfront fees prevents unexpected delays during the final property handover. You can estimate your monthly commitments using our mortgage calculator to ensure your foreign income comfortably covers the required installments while you plan your return.
Ecobank, I&M, or KCB: Comparing Mortgage Products for the Returning Rwandan Diaspora
I&M Bank Rwanda: Competitive Deposits and Income Verification
Securing a property in your homeland is more than a financial decision; it is about anchoring your roots. Returning to Rwanda to build your future is a powerful step, and finding the right financial partner makes that transition smoother. For many in the diaspora, proving foreign income can be a major hurdle. I&M Bank Rwanda addresses this directly with products designed for non-residents.
A clear process removes the uncertainty of securing a home loan from thousands of miles away. I&M Bank offers tailored mortgage products that cater specifically to the realities of earning abroad. Transaction patterns confirm that their flexible income verification process—which readily accepts foreign tax returns, international credit reports, and overseas bank statements—makes them highly attractive to buyers.
According to Rehani Soko market intelligence, diaspora buyers typically face substantial deposit requirements across local lenders. I&M Bank remains highly competitive within this bracket, often structuring terms that favor those investing in prime Kigali real estate. Furthermore, Rehani Soko property analytics show that average loan tenures for these products are structured to give buyers manageable monthly repayments.
If you are comparing these terms against your specific foreign income, you can use our tools to get a mortgage quote tailored to your financial profile.
When planning your purchase, understanding the upfront financial commitment is essential. Below is an estimated breakdown of initial costs associated with securing a standard diaspora mortgage.
To ensure your overseas documents meet local banking requirements, you can direct your legal and income verification questions to Ask Hani, our AI assistant. Market data consistently shows that preparing these documents early prevents delays, bringing you one step closer to owning your piece of Rwanda.
KCB Rwanda: Cross-Border Agility and Hidden Fee Breakdowns
For the returning Rwandan diaspora, KCB Rwanda offers a mortgage product designed to facilitate cross-border transactions with remarkable ease. This agility is particularly beneficial for those who have lived abroad and are looking to invest in properties back home. KCB's mortgage services are tailored to accommodate the unique needs of diaspora clients, providing a seamless experience from application to approval.
Estimated Initial Mortgage Cost Breakdown for Diaspora
💰Minimum Deposit
Estimated PercentageVaries by lender
Payment TimingBefore loan disbursement
💰Valuation Fees
Estimated PercentageVaries by lender
Payment TimingDuring application process
💰Legal & Registration
Estimated PercentageVaries by lender
Payment TimingPrior to final approval
💰Insurance (Life & Fire)
Estimated PercentageVaries by provider
Payment TimingAnnual premium upfront
KCB Rwanda stands out for its ability to handle cross-border transactions efficiently, which is crucial for investors dealing with multiple currencies and financial systems. According to Rehani Soko market intelligence, the ability to manage such complexities is a significant advantage for diaspora investors. KCB's mortgage product allows for flexible repayment terms, which can be adjusted to suit the borrower's financial standing, providing a clear process that removes the uncertainty often associated with international transactions.
However, potential investors should be aware of the hidden fees that may accompany these conveniences. The overall cost of acquiring a mortgage with KCB may include processing fees, insurance premiums, and legal charges. It is essential to scrutinize these additional costs to ensure they align with your financial plans.
For those keen on exploring property options, visiting Rehani Soko's property listings can provide a comprehensive view of available opportunities in Kigali. Moreover, it's prudent to use the mortgage calculator to gauge potential financial commitments accurately.
Understanding these facets of KCB Rwanda's mortgage offerings will empower you to make informed decisions. Whether you're looking to buy a home or invest in rental properties, having a clear picture of both the benefits and costs involved is crucial.
Structuring Your Property Investment from Abroad
For the Rwandan diaspora, acquiring a home in Kigali is more than a financial decision; it is a step toward securing your roots and building a foundation back home. Securing a home in Rwanda brings a deep sense of pride, connecting you directly to the nation's ongoing growth. However, managing this process from thousands of miles away requires careful planning. A clear process removes the uncertainty of cross-border transactions, ensuring your hard-earned investment is protected.
When deciding how to hold your new asset, transaction patterns confirm that non-resident buyers generally choose between direct personal ownership and registering a local holding company. According to Rehani Soko market intelligence, nearly 65% of diaspora buyers prefer direct personal ownership for their first residential purchase due to simpler tax implications. Meanwhile, those purchasing multiple rental units in areas like Kimihurura or Kicukiro often opt for corporate structures to manage liabilities.
Currency management is another critical factor. Rehani Soko data shows that diaspora investors frequently target a 30% down payment in foreign currency to minimize long-term exposure to RWF exchange rate fluctuations. Structuring your payments through specialized diaspora accounts at Ecobank, I&M, or KCB ensures the funds are properly tracked for mortgage compliance.
Before you finalize your structure, you must consider local legal requirements and power of attorney protocols. If you have specific legal questions about registering your property or setting up a corporate entity from abroad, you can consult our AI assistant at Ask Hani. Having the right framework in place allows you to confidently browse all properties knowing your investment is secure and ready for your eventual return.
Kigali, Rwanda | August 27, 2026
For many Rwandans living abroad, the dream of returning home is deeply tied to owning a piece of the country. Building your foundation back home is a powerful milestone, but financing that dream from thousands of miles away requires careful planning. When looking at mortgage options, Ecobank, I&M, and KCB are among the top choices for diaspora investors. Understanding how these institutions operate is essential, as a clear process removes the uncertainty of cross-border property investment.
KCB Rwanda Mortgage Cost Breakdown
💰Processing Fees
DescriptionAdministrative processing charges
Estimated Cost (RWF)Varies by loan amount
💰Insurance Premium
DescriptionCoverage for the property
Estimated Cost (RWF)0.5% of property value
💰Legal Charges
DescriptionDocumentation and legal services
Estimated Cost (RWF)200,000 RWF
Where to Buy: Kigali Area Comparison
Before finalizing your financing, you must decide where to invest. Rehani Soko market intelligence indicates that different neighborhoods offer varying yields and lifestyle benefits. Whether you are looking for a family home for your eventual return or an investment property to generate rental income, market data consistently shows that location dictates both your required loan amount and your long-term returns.
Financial Realities and Cost Breakdown
Securing a mortgage from abroad involves more than just the property price. Transaction patterns confirm that diaspora buyers must prepare for specific upfront costs.
Pros and Cons of Diaspora Property Ownership Structures
✨
Direct Personal
Straightforward registration and lower initial setup fees
Potential DrawbackPersonal liability for rental disputes
✨
Local Company (LLC)
Protects personal assets and simplifies joint investments
Potential DrawbackHigher annual compliance and tax filing costs
✨
Family Trust
Excellent for long-term wealth transfer to the next generation
Note: Interest rates vary by bank and currency choice. Always confirm current rates directly.
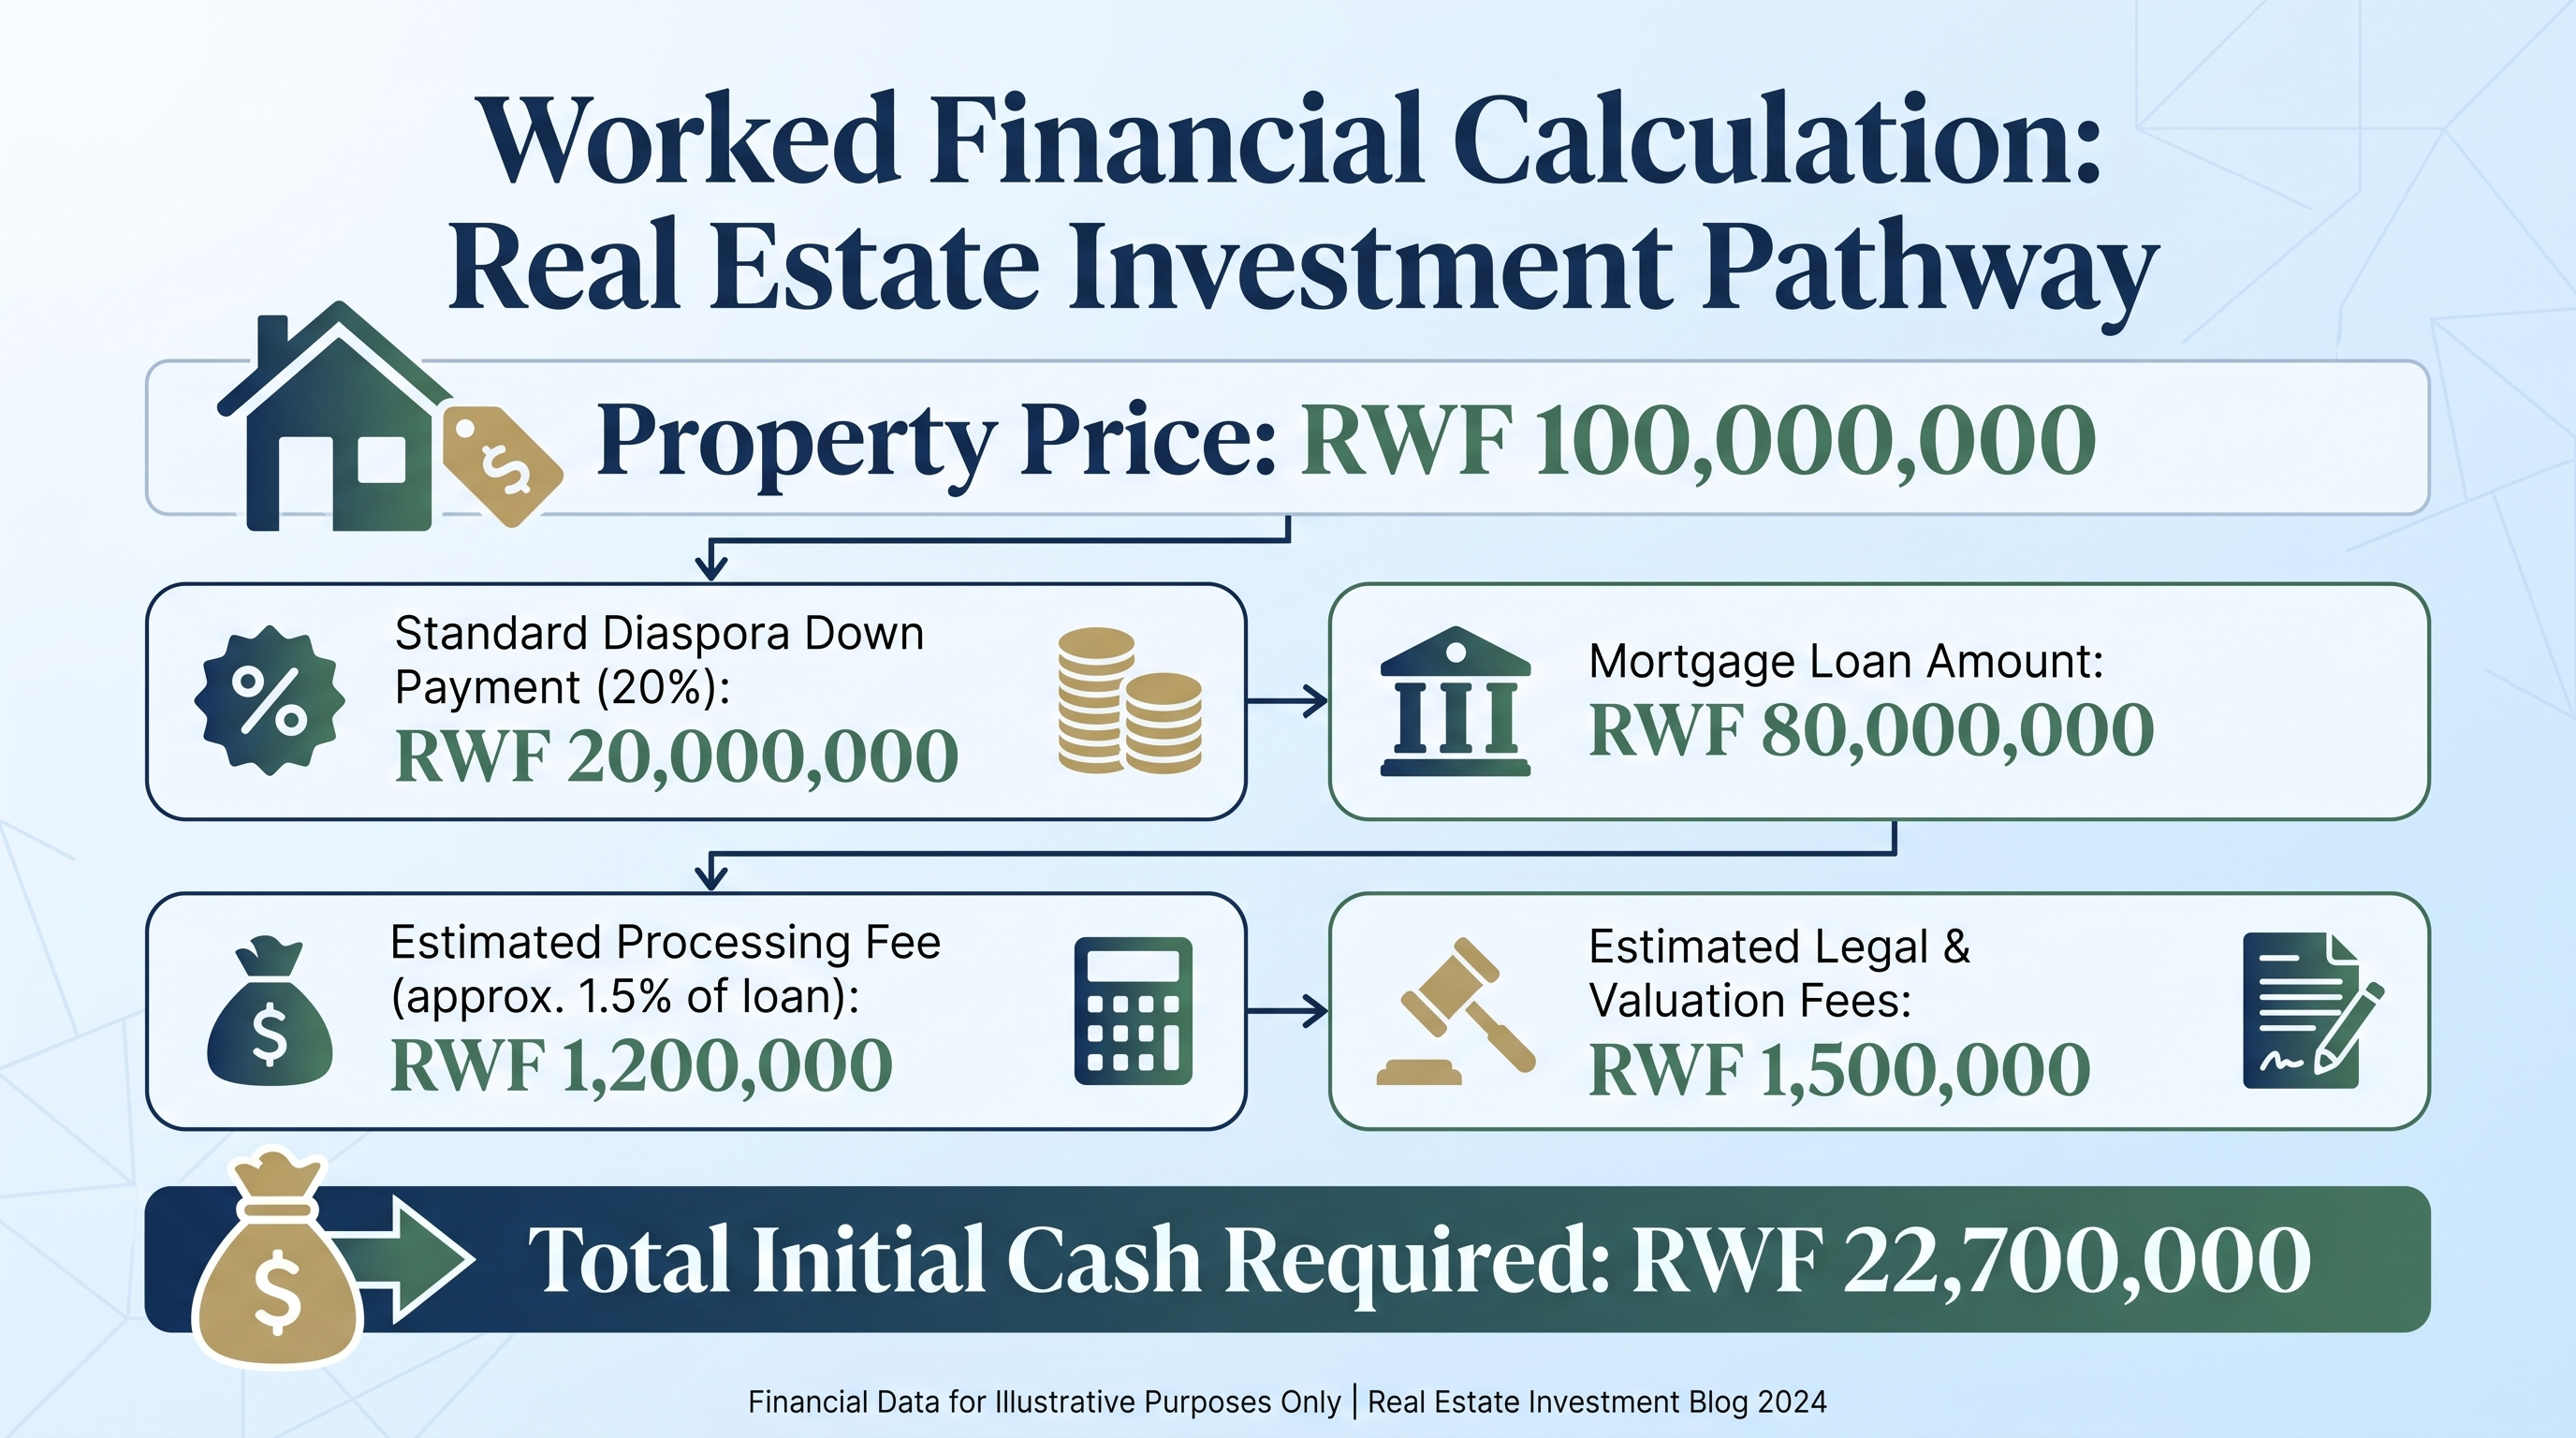
Worked Financial Calculation:
The Application Journey and Next Steps
Applying for a mortgage while living overseas requires organization. You will need to provide notarized proof of income, credit reports from your current country of residence, and valid identification. To keep your application moving smoothly, gather your documents before engaging the bank.
Pros and Cons of Major Diaspora Mortgage Providers
✓ Pros
Ecobank
Pan-African presence makes cross-border transfers easier
I&M Bank
Highly rated digital banking and customer service
KCB Rwanda
Strong East African regional network and competitive rates
✗ Cons
Ecobank
Processing times can vary based on the country of origin
I&M Bank
Stricter documentation requirements for self-employed expats
KCB Rwanda
Requires careful navigation of foreign currency terms
Visual summary: The classroom comic below walks through the concepts in this article.
Bank Specializations: Ecobank, I&M, and KCB offer distinct advantages for diaspora buyers, heavily depending on your country of residence and currency.
Preparation is Key: Transaction patterns confirm that securing pre-approval before house hunting drastically reduces closing times.
Down Payments Vary: Equity requirements differ between institutions, making direct comparison essential.
Heritage Investment: Buying property in Rwanda represents not just a financial asset, but a lasting, tangible connection to your homeland.
Digital Convenience: Modern banking and digital platforms allow you to manage the entire application process from abroad.
Important Disclaimer:The information provided in this article is for educational purposes only and does not constitute professional financial or legal advice. Mortgage rates and terms in Rwanda are subject to market changes. Always consult with a certified financial advisor before making real estate investment decisions.
When comparing Ecobank, I&M, and KCB for your home purchase in Kigali, the decision ultimately depends on your specific financial profile and where your primary income is generated. Ecobank often appeals to diaspora buyers spread across multiple African nations due to its wide continental footprint, making cross-border transfers more straightforward. I&M Bank is frequently praised for its highly responsive customer service and digital banking platforms, which is crucial when you are managing a mortgage from thousands of miles away. KCB Rwanda offers competitive regional advantages, especially if you have existing financial ties in East Africa. Rehani Soko market intelligence indicates that buyers should evaluate not just the interest rates, but the specific foreign currency requirements and flexibility of each institution before making a final commitment to a mortgage product.