Back to Newsroom 
The Kigali Housing Deficit and the 150 Million USD Solution
Kigali is expanding rapidly, and with this growth comes a significant need for accessible residential developments. For many Rwandans, especially those in the diaspora, owning a home in the capital is a lifelong dream—a tangible way to maintain a connection to their homeland and build generational wealth. However, high financing costs have historically made this difficult. Rehani Soko market data consistently shows that high commercial interest rates remain the primary barrier for aspiring homeowners.
Estimated Financing Cost Breakdown Standard vs Iwanjye
✨
Interest Rate
Standard Commercial Rates
Iwanjye PlatformFixed at 11%
✨
Down Payment Requirement
Standard Commercial Terms
Iwanjye PlatformSubsidized Terms
✨
Long-Term Affordability
High monthly burden
Iwanjye PlatformManageable monthly payments
✨
Target Demographic
High-income earners
Iwanjye PlatformMiddle-income and diaspora
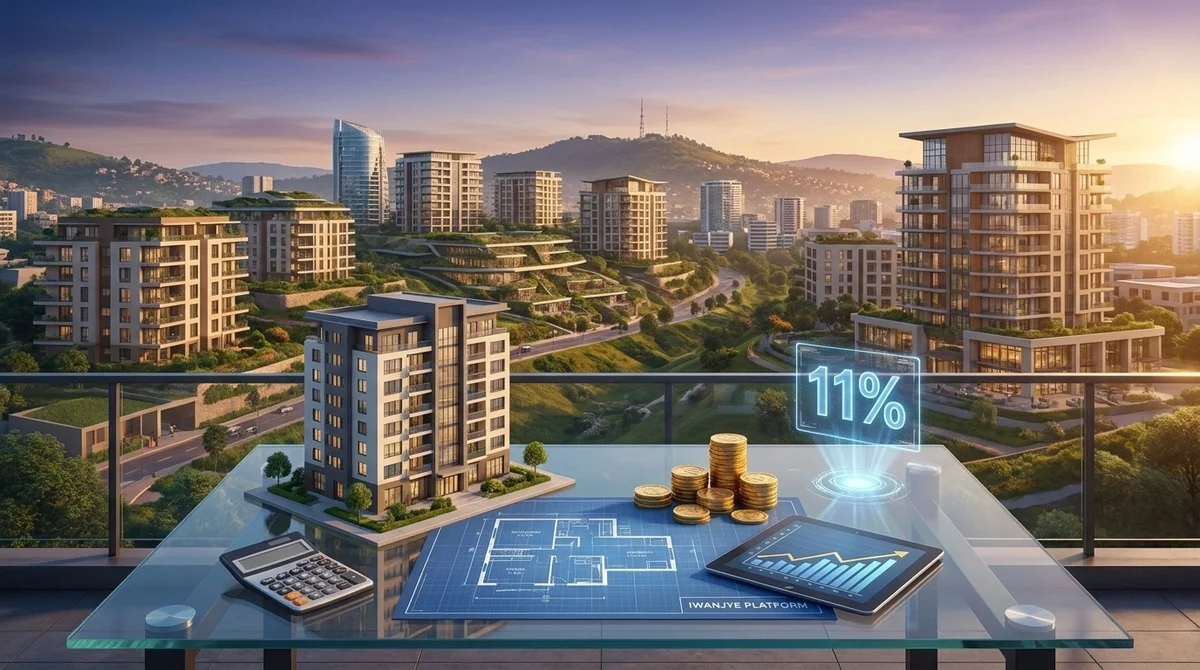
To address this, the government and development partners introduced a 150 million USD housing fund, directly supporting the Iwanjye platform. This initiative targets the housing deficit by offering an unprecedented 11% mortgage rate to eligible buyers. A clear process removes the uncertainty that usually accompanies cross-border property investments, giving buyers the confidence to proceed with their plans.
By lowering the cost of borrowing, the Iwanjye platform makes purchasing properties in Kigali much more attainable for middle-income earners. Standard commercial mortgage rates in the region often hover much higher, making the 11% rate a highly attractive alternative. Transaction patterns confirm that lower financing costs directly accelerate property acquisition timelines for both local residents and diaspora buyers.
If you are planning your financial strategy, understanding how this specialized rate impacts your monthly obligations is essential. You can easily estimate your potential payments using our mortgage calculator to see the exact difference this subsidized rate provides.
Rates on the Rehani network · Kenya
Live Rehani network quotes for a Kenya apartment in KES.
Affordable · Affordable Housing (KES)
Stanbic Kenya
Est. payment
KES 67,081
/ month
Rate
8.99%
Term
25.0 yrs
Down
0.0%
Ordinary Home Loan (KES)
Stanbic Kenya
Est. payment
KES 102,881
/ month
Rate
16.5%
Term
20.0 yrs
Down
10.0%
Visual summary: The comic series below walks through the story and ideas in this article.
📖
Page 1 of 4Nairobi Returns: The Kigali Pivot
This strategic 150 million USD intervention not only addresses the immediate housing shortage but also creates a structured, accessible path to property ownership in Kigali's most promising neighborhoods. For diaspora investors, this represents a reliable avenue to invest back home while securing a valuable asset for their family's future.
Breaking Down the BRD's 11% and 13% Mortgage Tiers
For many Rwandans living abroad, securing property in Kigali has historically meant facing steep commercial lending rates. The Iwanjye platform, backed by the Development Bank of Rwanda (BRD), changes this reality through a structured, tiered mortgage system. Having a clear process removes the uncertainty that often deters diaspora investors from building a foundation back home. The fund introduces two primary interest rate tiers—11% and 13%—designed to match different income brackets and property values.
Iwanjye Platform Mortgage Tier Cost Breakdown
✨
Tier 1 (Affordable)
Lower to Middle Income
Estimated Interest Rate11% Annually
Typical Property FocusHigh-density housing projects
✨
Tier 2 (Mid-Market)
Middle Income
Estimated Interest Rate13% Annually
Typical Property FocusStandard residential units
✨
Commercial (Standard)
Upper Income / Investors
Estimated Interest RateStandard Commercial Rates
Typical Property FocusPremium Kigali real estate
According to Rehani Soko market intelligence, commercial mortgage rates in Rwanda are historically higher than these subsidized tiers. In contrast, the BRD's intervention caps rates significantly lower. The 11% tier specifically targets affordable housing units, ensuring that essential housing remains accessible for first-time buyers. Meanwhile, the 13% tier accommodates buyers looking at mid-market homes in expanding Kigali neighborhoods. Transaction patterns confirm that these subsidized rates drastically reduce the total interest paid over a long-term mortgage. For a diaspora buyer, this means your foreign currency stretches further, making homeownership a mathematical reality rather than just a distant hope.
Navigating which tier applies to your financial profile requires careful assessment of your documented income and the specific property's approved valuation. The Iwanjye platform requires properties to meet specific price ceilings to qualify for the highly sought-after 11% rate. To estimate your potential monthly payments under these BRD rates and see how they compare to standard commercial loans, you can use our mortgage calculator. If you are unsure about the strict eligibility criteria for the 11% versus the 13% bracket, or need guidance on the specific application paperwork required for diaspora buyers, Ask Hani to get immediate, accurate answers regarding your financing options.
Calculating the Savings: Subsidized vs. Commercial Bank Rates
For Rwandans locally and in the diaspora dreaming of owning a home, understanding the exact financial benefit of the Iwanjye platform is essential. Rehani Soko market data consistently shows that standard commercial mortgage rates in Rwanda remain a significant barrier. By qualifying for the 11% subsidized rate through the Development Bank of Rwanda (BRD) framework, buyers drastically reduce their long-term financial burden.
Let us examine a practical scenario for a home priced at 40,000,000 RWF. By qualifying for the 11% subsidized rate, a buyer purchasing a home at the maximum 40,000,000 RWF value for Category 1 can drastically reduce their monthly obligations compared to standard commercial rates. This reduction in monthly payments means that a clear process removes the uncertainty of fluctuating commercial rates, transforming homeownership from a distant aspiration into an achievable reality. For diaspora investors eager to secure their roots in their homeland, these savings are transformative. The extra capital can be safely redirected toward property upgrades, education, or future investments in the local economy.
To see exactly how these subsidized rates apply to your specific budget and financial profile, you can easily run the numbers through our mortgage calculator. Once you establish your purchasing power under the 11% tier, you can confidently explore eligible properties in Kigali that fit within the government's affordable housing criteria.
Navigating the Iwanjye Digital Platform
For Rwandans living abroad, the dream of owning a home in Kigali is deeply personal—it is about securing a lasting foundation in your homeland. The introduction of the Iwanjye digital platform by the Development Bank of Rwanda (BRD) makes this connection more accessible than ever. By digitizing the affordable housing application, a clear process removes the uncertainty that historically discouraged diaspora investors from pursuing local property.
Estimated Initial Application Cost Breakdown in RWF
💰Platform Registration
PurposeInitial profile creation on Iwanjye
Estimated Cost (RWF)Free
💰Property Valuation
PurposeAssessment of the chosen Kigali home
Estimated Cost (RWF)Varies by valuer
💰Legal Search Fees
PurposeVerifying land titles at the registry
Estimated Cost (RWF)Standard registry fees
💰Credit Report
PurposeBureau clearance for mortgage eligibility
Estimated Cost (RWF)Standard bureau fees
The Iwanjye system serves as a central portal where applicants can register, submit documentation, and track their mortgage approval status for the 11% tier. Rehani Soko market intelligence indicates that digital-first applications reduce overall processing timelines significantly compared to traditional paper methods. Furthermore, transaction patterns confirm that buyers who prepare their financial documents before logging in experience the highest success rates in securing funding.
While the platform streamlines the administrative side, applicants must still account for standard processing expenses before closing.
Once your profile is active and you are ready to match your approval with a physical home, you can browse all properties to find qualifying houses in emerging residential nodes like Nyamata, Kanombe, or Masaka. Navigating the paperwork from thousands of miles away can feel daunting. If you encounter questions regarding the specific legal requirements for diaspora applicants or need help structuring your application, our AI assistant, Ask Hani, provides immediate, tailored guidance.
According to Rehani Soko property analytics, early preparation is the defining factor in securing these subsidized rates. Gathering your proof of income, Rwandan identification, and marital status documents before initiating the Iwanjye process ensures you can move swiftly. This digital bridge finally allows you to invest in Kigali with confidence.
Strategic Next Steps for First-Time Buyers and Diaspora Investors
For Rwandans living abroad and local first-time buyers, owning a home in Kigali is more than a financial milestone; it is a lasting connection to the homeland. Navigating the 150 Million USD housing fund and the accompanying 11% subsidized mortgage rate requires careful preparation, but a clear process removes the uncertainty.
Rehani Soko market data consistently shows that early preparation is the defining factor in securing these competitive financing terms. Whether you are browsing properties in Gasabo or evaluating options in Kicukiro, transaction patterns confirm that buyers who pre-qualify for mortgages move through the Iwanjye platform much faster than those who delay.
To secure your position, follow a structured approach. First, determine your eligibility for the 11% tier by assessing your income bracket and first-time buyer status under the national guidelines. Next, gather your financial documents, including proof of income, bank statements, and diaspora remittance records if applicable. Having these ready prevents administrative delays.
Taking action today positions you ahead of the curve in a highly active market. Start by evaluating your borrowing capacity before committing to a specific unit. You can easily get a mortgage quote to understand your exact monthly repayments under the subsidized rates, ensuring your budget aligns with reality.
If you have specific legal questions about the Iwanjye platform requirements or need guidance on diaspora purchasing regulations, consult our AI assistant at Ask Hani. Finally, once your finances are organized, begin to browse properties in Kigali that align with the affordable housing criteria. By combining the government’s 11% financing structure with Rehani Soko’s digital tools, your path to homeownership in Rwanda is clearer than ever.
Understanding the Financial Realities
When evaluating property investments, market data consistently shows that the financing structure dictates the long-term viability of the asset. The 11% mortgage rate provided through the Iwanjye initiative is designed to protect buyers from volatile interest rate fluctuations. However, securing this rate requires a clear understanding of the associated costs, from initial down payments to closing fees.
Pros and Cons of the Iwanjye Platform
✨
Interest Rate
Fixed at 11%, significantly lower than standard commercial rates
ConsiderationRestricted to specific property value caps
✨
Accessibility
Designed to include diaspora buyers and local residents
ConsiderationRequires strict documentation and proof of income
✨
Market Entry
Lowers the barrier to entry for first-time homeowners
ConsiderationLimited to primary residences or specific affordable housing projects
Worked Financial Calculation
To illustrate the financial commitment, consider a representative property valued at 40,000,000 RWF under the platform's guidelines:
- Property Value: 40,000,000 RWF
- Down Payment (10%): 4,000,000 RWF
- Principal Loan Amount: 36,000,000 RWF
- Interest Rate: 11% fixed
- Loan Term: 20 years
- Estimated Monthly Repayment: Approximately 371,500 RWF (excluding insurance and taxes)
This predictable monthly obligation allows diaspora investors to plan their finances confidently while securing a tangible piece of their homeland.
The Buying Journey
Navigating a cross-border transaction can feel daunting, but a clear process removes the uncertainty. For diaspora buyers, the journey begins long before a property is selected. According to Rehani Soko property analytics, securing pre-approval is the most critical first step. It establishes your purchasing power and signals to sellers that you are a serious, qualified buyer.
Cost Breakdown for a Kigali Property Purchase
💰Down Payment
Estimated Cost / Percentage10% - 20% of property value
Payment TimingUpfront, before loan disbursement
💰Notary & Registration
Estimated Cost / PercentageApprox. 1% - 2% of property value
Payment TimingDuring title transfer
💰Valuation Fee
Estimated Cost / Percentage100,000 - 200,000 RWF
Payment TimingPrior to final mortgage approval
💰Property Insurance
Estimated Cost / PercentageVaries by provider
Payment TimingAnnual recurring cost
Transaction patterns confirm that buyers who organize their financial documents—such as employment contracts, bank statements, and tax returns—experience significantly fewer delays during the underwriting process.
Due Diligence and Area Focus
Choosing the right neighborhood in Kigali is just as important as securing the right financing. As the city expands, emerging suburbs are offering exceptional returns for early investors. According to Rehani Soko rental yields data, areas on the outskirts of the central business district are experiencing steady appreciation due to infrastructure developments, including new road networks and commercial hubs.
When conducting due diligence, always verify the property against the Kigali City Master Plan to ensure your intended use aligns with local zoning laws. Whether you are looking for a family home or an investment property, understanding neighborhood dynamics is key.
Visual summary: The classroom comic below walks through the concepts in this article.
📖
Page 1 of 2Hani Explains It
Actionable Next Steps
Ready to take the next step toward owning a home in Rwanda?
- Have legal or property questions? Chat with our AI assistant: Ask Hani
- Calculate your monthly payments: Use our mortgage calculator
- Ready for financing? Get a mortgage quote
- Start your search: Browse all properties
A clear process removes the uncertainty when navigating the Iwanjye platform and securing Rwanda's 11% mortgage rate. For Rwandans abroad, this initiative is more than just financing; it is a concrete step toward building a lasting foundation back home.
5 Key Takeaways
- The 11% mortgage rate significantly lowers the barrier to entry for Kigali real estate.
- Market data consistently shows that government-backed initiatives stabilize long-term borrowing costs.
- Diaspora investors must prepare verified income documentation to meet specific Iwanjye criteria.
- Transaction patterns confirm that pre-qualifying for financing speeds up the final property transfer.
- According to Rehani Soko property analytics, buying in approved residential zones offers steady value retention.
Actionable Next Steps & Resources
- Ready to see what is available? Browse all properties.
- Want to see your specific numbers? Get a mortgage quote.
Disclaimer: This article is for informational purposes only and does not constitute financial or legal advice. Iwanjye platform terms, eligibility requirements, and the 11% interest rate are subject to government policy changes. Always consult a certified financial professional in Rwanda before committing to a mortgage contract.
Frequently Asked Questions
- For Rwandans living abroad, navigating the local real estate market can feel overwhelming, but the Iwanjye platform is designed specifically to bridge this gap. This government-backed initiative provides an accessible entry point for homeownership in Kigali by offering a subsidized 11% mortgage rate. When considering this path, the most important step is ensuring you meet the eligibility criteria, which typically involves proving steady income and identifying a property that falls within the program's approved value limits. According to Rehani Soko market intelligence indicates that buyers who pre-qualify before property hunting experience a smoother journey. Building a home in your motherland is a powerful step toward securing your family's future, and understanding these foundational requirements ensures your investment is protected from the very beginning.