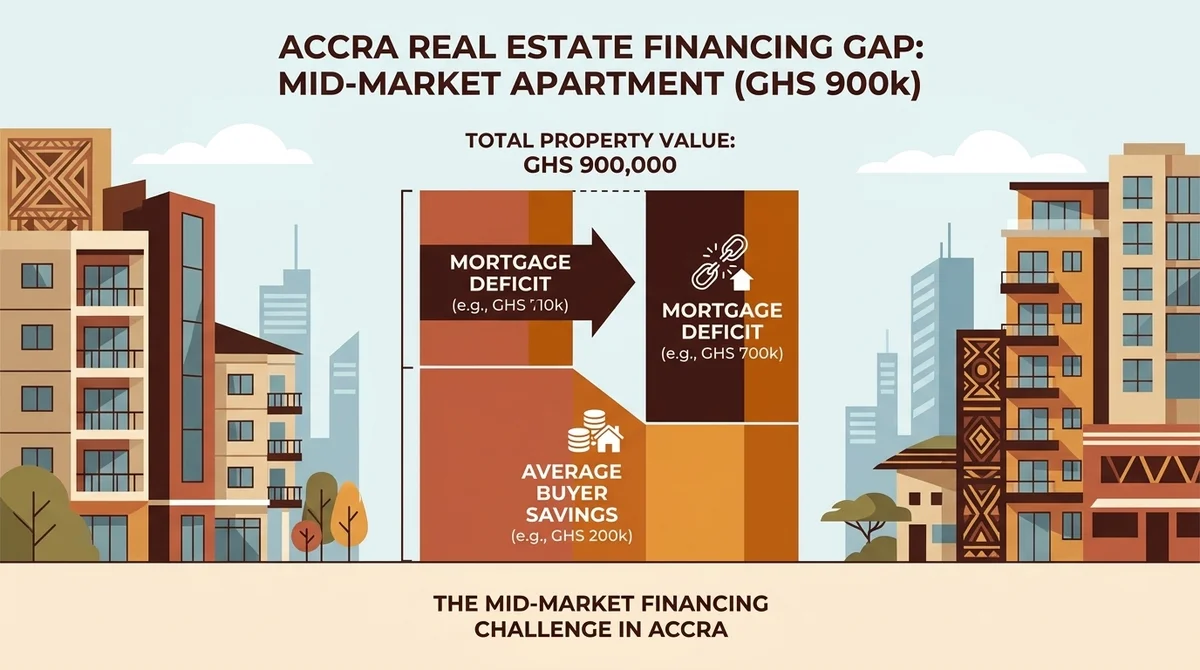
Navigating the financial landscape of purchasing a GHS 900,000 apartment in Accra presents a unique set of challenges, particularly for mid-market buyers. The Ghanaian real estate market has seen a dynamic shift, with mid-market properties emerging as a critical segment. However, securing adequate financing remains a significant hurdle for many potential homeowners.
Mid-Market Mortgage Factors in Accra
✨
Interest Rate
Average rate for mortgages in Ghana
Current Status21%
✨
Property Demand
Demand for mid-market apartments in Accra
Current StatusHigh
✨
Mortgage Accessibility
Availability of suitable mortgage products
Current StatusLimited
According to the Bank of Ghana, interest rates have seen fluctuations, affecting mortgage affordability. Currently, interest rates hover around 21%, which poses a substantial financial commitment for buyers seeking mid-range housing. This situation underscores the importance of understanding the mid-market mortgage gap that exists in Accra, where the demand for properties does not always align with the availability of financing options.
Rehani Soko market intelligence indicates that while the demand for mid-market apartments is robust, the financing options available do not adequately cater to this segment. Prospective buyers often find themselves caught between the limitations of high-interest loans and the challenge of assembling a sizable down payment. This gap highlights the need for tailored mortgage solutions that can bridge the divide and make homeownership more accessible.
For those considering entering the market, it’s essential to approach the buying process with a clear understanding of financial obligations and potential risks. Buyers are encouraged to utilize tools like the mortgage calculator offered by Rehani Soko to better grasp their financial standing. Additionally, exploring mortgage options through the Rehani Soko mortgage platform can provide insights into feasible financing solutions.
Visual summary: The comic series below walks through the story and ideas in this article.
📖
The Hustle and The Home
Page 1 of 5
In conclusion, while the mid-market segment in Accra presents promising opportunities, understanding the financial landscape and preparing adequately for the mortgage process is crucial. By leveraging tools and resources available through platforms like Rehani Soko, buyers can navigate this complex environment with greater confidence and clarity.
Why Lenders Reject Lower Loan Amounts
Securing a mortgage for a GHS 900,000 apartment in Accra can be a significant financial milestone. However, it often comes with challenges, particularly when lenders hesitate to approve lower loan amounts. Understanding the reasons behind this can help you better prepare for the financing process.
Cost Breakdown for Loan Processing
💰Operational Costs
DescriptionFixed costs for processing loans
Impact on Loan ApprovalHigh impact on smaller loans
💰Interest Returns
DescriptionRevenue from interest over loan term
Impact on Loan ApprovalHigher for larger loans
💰Risk Assessment
DescriptionEvaluation of borrower's creditworthiness
Impact on Loan ApprovalAffects loan approval
One primary reason lenders reject smaller loan amounts is the cost inefficiency. According to the Bank of Ghana, operational costs for processing loans remain relatively constant regardless of the loan size. Therefore, smaller loans yield lower returns for lenders, making them less attractive. Additionally, Rehani Soko data shows that lenders are more inclined towards larger loans that promise higher interest returns over time.
Another factor is the perceived risk. Lenders assess the borrower's financial stability and the property's value to determine the loan's risk level. Smaller loans might suggest a borrower with limited financial capacity, which could increase default risk. This is particularly relevant in Accra, where property values can fluctuate. According to Ghana Statistical Service data, property prices in certain Accra neighborhoods have seen a 5% annual increase, which might not reflect consistently in all areas, impacting perceived risk.
For those considering financing options, it is crucial to understand these dynamics and explore strategies to strengthen your mortgage application. One effective approach is to improve your credit score, as this can significantly influence lender decisions. Additionally, presenting a substantial down payment can enhance your credibility and reduce the loan-to-value ratio, making your application more appealing to lenders.
The Mid-Market Mortgage Gap in Accra
For more insights into navigating the property market in Accra, consider exploring properties in Accra or using our mortgage calculator to plan your finances effectively. Understanding these elements can help you make informed decisions and increase your chances of securing the right mortgage for your needs.
The Cash-Heavy Reality for Diaspora and Local Buyers
Financing a GHS 900,000 apartment in Accra presents a unique set of challenges for both local and diaspora buyers. The process requires careful financial planning, as the substantial upfront cash requirements can be daunting. According to Rehani Soko market data, the average down payment for such a property is typically 20%, amounting to GHS 180,000. This figure alone highlights the significant cash reserve needed even before considering additional costs.
For many diaspora buyers, the dream of owning property in their homeland often involves navigating complex financial landscapes. The Ghana Statistical Service (GSS) reports that while remittances contribute significantly to the national economy, they do not always translate into smooth property transactions. Diaspora buyers must often contend with fluctuating exchange rates and transfer fees, which can affect their purchasing power.
Local buyers, on the other hand, face their own set of challenges. The Bank of Ghana notes that interest rates remain a crucial factor in mortgage affordability. With rates hovering around 20%, potential homeowners must weigh the long-term financial implications of their investment. Moreover, the additional costs such as legal fees, property taxes, and insurance can add up quickly, making it essential to plan meticulously.
Understanding these financial commitments is crucial for any buyer. For those seeking guidance, tools like the mortgage calculator on Rehani Soko's platform can provide valuable insights into monthly payments and overall affordability. Additionally, engaging with the Ask Hani tool can help address any legal or procedural questions, ensuring that both local and diaspora buyers make informed decisions in their property journey.
Alternative Financing: Developer Payment Plans
When it comes to financing a GHS 900,000 apartment in Accra, exploring alternative financing options like developer payment plans can be a strategic move. These plans offer flexibility and can be tailored to meet the unique financial circumstances of buyers, particularly beneficial in a market where traditional mortgage options might be limited or cumbersome.
Cost Breakdown for a GHS 900,000 Apartment
💰Down Payment
Percentage of Total Cost20%
Estimated Amount (GHS)180,000
💰Legal Fees
Percentage of Total Cost3%
Estimated Amount (GHS)27,000
💰Property Taxes
Percentage of Total Cost1.5%
Estimated Amount (GHS)13,500
Developer payment plans often allow buyers to secure a property with a lower initial cash outlay, making home ownership more accessible. Typically, these plans involve a structured payment schedule where a buyer pays a portion of the purchase price upfront, followed by staggered payments aligned with construction milestones or completion dates. This approach can significantly reduce the immediate financial burden on buyers, allowing them to manage cash flow more effectively.
According to Rehani Soko market intelligence, developer payment plans have become increasingly popular in Accra due to their adaptability and the growing demand for flexible financing solutions. These plans can also provide a buffer against fluctuating interest rates, which, according to the Bank of Ghana, have shown variability in recent years. This stability can be particularly appealing to diaspora buyers who may face challenges in securing traditional financing due to credit history gaps or income verification issues.
For those considering this option, it’s crucial to conduct thorough due diligence to ensure the developer's credibility and the project's viability. Potential buyers can explore properties in Accra on Rehani Soko to find projects offering such plans. Additionally, using tools like the mortgage calculator can help assess the affordability of different financing scenarios.
This table illustrates a typical payment structure, highlighting how costs are distributed over time, making it easier for buyers to plan their finances. By understanding these dynamics, potential homeowners can confidently navigate the process of acquiring property in Accra.
Long-Term Outlook for Accra's Housing Finance
The future of housing finance in Accra presents both challenges and opportunities, especially for those considering a GHS 900,000 apartment investment. As Ghana's economy continues to evolve, so does the landscape of property financing. According to the Ghana Statistical Service, the GDP growth rate has shown resilience, offering a promising backdrop for real estate investments. However, the Bank of Ghana's interest rate policies will play a critical role in shaping accessibility to mortgage products over the coming years.
A key aspect to consider is the potential for fluctuating interest rates, which could impact mortgage affordability. Currently, interest rates in Ghana are influenced by both domestic economic conditions and global market trends. As we look to the future, strategic financial planning will be crucial for buyers aiming to optimize their investment returns. Rehani Soko market data shows a steady increase in property prices, suggesting a favorable long-term capital appreciation for early investors.
For those in the diaspora and local buyers, understanding the cost breakdown of financing can offer clarity and confidence. The initial costs, including down payments and fees, are significant, but long-term planning can mitigate these challenges. Buyers are encouraged to explore various mortgage options and utilize tools like the mortgage calculator to better understand their financial commitments.
Navigating the complexities of Accra's housing finance requires a blend of caution and optimism. By keeping abreast of economic indicators and leveraging available resources, such as the AI assistant from Rehani Soko, investors can position themselves advantageously in the market. As the city grows and evolves, the housing sector is poised to offer substantial returns for those ready to take informed steps forward.
Conclusion
Financing a GHS 900,000 apartment in Accra is a significant financial commitment, and understanding the intricacies of the process is crucial. Here are five key takeaways to consider:
Budgeting is Essential: A clear process removes the uncertainty around financing. Make sure to account for additional costs such as legal fees and property taxes.
Market Insights Matter: According to Rehani Soko property analytics, understanding market trends and price predictions can give you a competitive edge.
Consider Financing Options: Explore various mortgage options to find what best suits your financial situation. Use tools like the mortgage calculator to plan effectively.
Location Comparison: Different areas in Accra offer varying price points and investment potentials. Choosing the right location can significantly impact your returns.
Consult the Experts: For any legal or financial questions, Ask Hani for tailored advice.
Important Disclaimer
This article provides general information for informational purposes only and does not constitute financial advice. Always consult with a qualified financial advisor or legal professional for personalized advice specific to your situation.
Visit Rehani Soko for comprehensive property listings and further insights.
By staying informed and utilizing available resources, you can navigate the property market in Accra with confidence and clarity.
Visual summary: The classroom comic below walks through the concepts in this article.
📖
Hani Explains It
Page 1 of 2
Frequently Asked Questions
As a first-time buyer in Accra, it's essential to approach the process with a blend of curiosity and caution. Start by assessing your financial readiness, ensuring you have a clear understanding of your budget and financing options. Rehani Soko offers a mortgage calculator to help you estimate monthly payments. Next, research different neighborhoods to find one that aligns with your lifestyle and budget. Utilize resources like Rehani Soko’s property listings to compare options. Consider the long-term potential of the area, including infrastructure developments and property appreciation trends. Finally, engage a reputable local real estate agent who understands the Accra market dynamics. They can guide you through the legal and procedural steps, ensuring a smooth transaction. Remember, a clear process removes the uncertainty, making your investment a well-informed decision.