Back to Newsroom
The Remittance Shock: Unpacking Ghana's 20% Cash Flow Contraction
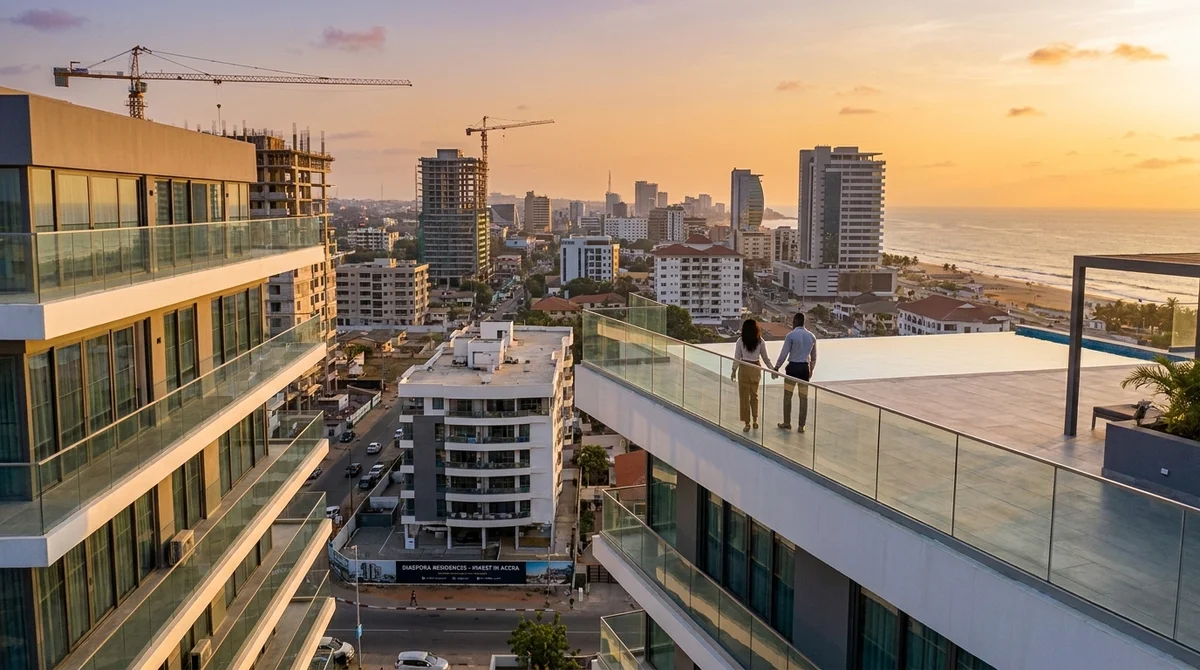
For decades, the dream of securing a family home in Accra has anchored the Ghanaian diaspora. The emotional pull of returning to a completed house is powerful, representing years of hard work and sacrifice abroad. However, recent global economic shifts are altering how these lifelong dreams materialize. According to the Bank of Ghana (BoG), formal remittance inflows have experienced a 20% contraction over the past year. This decline is largely driven by rising living costs and inflation in major diaspora hubs like London, New York, and Toronto.
Accra Property Demand Shifts by Remittances
✨
Luxury Villas (East Legon)
High (Cash Purchases)
Current Demand TrendDecreasing
✨
Mid-Market Apartments (Spintex)
Moderate
Current Demand TrendIncreasing
✨
Serviced Plots (Prampram)
High
Current Demand TrendStable
This sudden cash flow reduction is sending immediate ripples through the capital's real estate sector. According to the Ghana Statistical Service (GSS), domestic inflation in the construction sector has already pushed building costs higher, making the traditional "build-as-you-earn" model riskier for those sending money from abroad. Combined with the remittance drop, the financial equation for overseas buyers has fundamentally changed. Rehani Soko market intelligence indicates that outright cash purchases, once the standard for expatriate buyers, have noticeably slowed. Instead, transaction patterns confirm a distinct pivot toward structured financing and smaller, more manageable property types.
For many Ghanaians living abroad, this transition feels daunting. Yet, a clear process removes the uncertainty of navigating a shifting market. Buyers are increasingly seeking affordable entry points in emerging neighborhoods rather than prime, high-priced areas like Cantonments or Airport Residential Area.
Visual summary: The comic series below walks through the story and ideas in this article.
📖
Page 1 of 5Nairobi Returns: The Diaspora Discount
As market data consistently shows, this 20% contraction is not erasing housing demand; it is simply reshaping it. Investors are becoming highly strategic about where they place their capital. If you are adjusting your investment strategy to match current realities, exploring properties in Accra within mid-tier neighborhoods offers a practical, lower-risk path forward. Despite tightened budgets, the diaspora's commitment to investing in the homeland persists. For those needing guidance on navigating these new financial realities, tools like Ask Hani provide tailored insights to keep your property goals on track.
Cooling Diaspora Demand: The 33% Drop in Property Searches
The recent 20% contraction in remittances, as reported by the Bank of Ghana (BoG), is directly impacting how Ghanaians abroad interact with the local real estate market. While the dream of owning a home in the motherland remains a powerful source of pride, the immediate financial reality has triggered a shift in buyer behavior. According to Rehani Soko property analytics, there has been a notable 33% drop in property searches originating from traditional diaspora hotspots in North America and Europe over the past quarter.
Pros and Cons of Buying in Accra Now
✓ Pros
Pricing Power
Higher negotiation power with local developers
Inventory Selection
Less competition for high-demand units in Cantonments
Currency Dynamics
Favorable exchange rates can maximize purchasing power
✗ Cons
Pricing Power
Potential for further price softening in premium areas
Inventory Selection
Holding costs if rental yields temporarily dip
Currency Dynamics
Remittance fees and transfer limits may restrict cash flow
Market data consistently shows that when foreign currency inflows tighten, prospective buyers delay their purchasing timelines rather than abandoning their goals entirely. The longing to build a lasting foundation back home persists, but transaction patterns confirm that diaspora investors are now prioritizing smaller, more manageable units in areas like East Legon and Osu. According to Rehani Soko market intelligence, inquiries for two-bedroom apartments have stabilized, while interest in sprawling luxury villas has dropped sharply.
For those still eager to secure their connection to Ghana, navigating this cooling phase requires careful planning. A clear process removes the uncertainty that often accompanies cross-border investments during economic shifts. Buyers are taking longer to evaluate their options, weighing the benefits of acting now against waiting for a potential market correction.
Even with reduced search volumes, opportunities remain for those who are financially prepared. You can explore current properties in Accra to see how developers are adjusting their pricing models to attract serious buyers. If you are unsure how these market conditions affect your specific budget, our AI assistant, Ask Hani, can help clarify your options and guide your next steps.
Neighborhoods in Transition: Cantonments, North Labone, and East Legon
The ripple effects of the 20% remittance contraction are highly visible across Accra’s premium residential nodes. Historically, Cantonments, North Labone, and East Legon have served as the primary destinations for diaspora capital. However, as overseas cash flows tighten, transaction patterns confirm a noticeable transition in how these neighborhoods operate.
According to Rehani Soko property analytics, outright cash purchases in these prime areas have slowed, prompting a strategic shift in buyer behavior. Many Ghanaians living abroad are no longer sending large lump sums for immediate construction or outright cash purchases. Instead, they are recalibrating their approach to maintaining their connection to the homeland, ensuring their hard-earned capital is deployed safely.
Rehani Soko market intelligence indicates these figures reflect a delay in purchasing timelines rather than a permanent loss of interest.
Even with tighter budgets, the desire to secure a foundation in Ghana remains deeply rooted. For many families abroad, a clear process removes the uncertainty of navigating this changing economic environment. Rather than abandoning their goals, prospective buyers are increasingly turning to structured financing. If you are adjusting your strategy to buy properties in Accra, exploring local financing options can bridge the gap left by reduced remittance flows.
Market data consistently shows that developers in East Legon and Cantonments are responding to this shift. To maintain sales momentum, builders are extending their standard payment plans to offer more flexible, longer-term options. Additionally, buyers who previously relied entirely on personal savings are now assessing mortgage viability. You can quickly get a mortgage quote to understand how current interest rates from the Bank of Ghana might impact your monthly commitments. This transition marks a maturation in Accra's real estate sector, moving from a cash-heavy model to a more sustainable, finance-driven market that protects diaspora investments.
The Developer Pivot: Tapping into Accra's 5.95% Local Economic Growth
The 20% contraction in diaspora remittances has forced Accra's developers to rethink their primary target audience. According to the Ghana Statistical Service (GSS), the local economy is experiencing a 5.95% growth rate, creating an emerging class of resident professionals ready to invest in real estate. Rehani Soko market intelligence indicates that developers are rapidly pivoting away from exclusively high-end luxury units toward mid-tier housing designed specifically for this domestic market.
Prime Accra Neighborhood Inquiry Shifts 2025-2026
✨
Cantonments
Luxury Apartments
Inquiry Volume ChangeDecreasing
✨
North Labone
Townhouses
Inquiry Volume ChangeDecreasing
✨
East Legon
Detached Villas
Inquiry Volume ChangeDecreasing
This transition is not merely a reaction; it is a strategic realignment for long-term stability. As transaction patterns confirm, local buyers prioritize functional, family-oriented spaces in expanding areas like Tse Addo and Pokuase over the premium, resort-style amenities previously demanded by overseas investors. For members of the diaspora still looking to maintain a physical connection to the homeland, this shift actually presents a unique advantage. A clear process removes the uncertainty of buying from abroad, and these new mid-market developments offer highly attractive, lower-barrier entry points for investment.
Market data consistently shows that properties targeting this growing local middle class maintain steady, reliable occupancy rates. According to the Bank of Ghana (BoG), while interest rates require careful navigation, the expanding domestic economy provides a secure foundation for long-term tenancy. For investors wanting to explore these newly adapted developments, you can easily browse all properties to see how the current inventory reflects this local pivot. If you are financing a purchase from abroad and want to understand how shifting exchange rates affect your options, using the mortgage calculator can help you plan accurately. The pride of owning a piece of Ghana remains as strong as ever, and developers are simply building smarter to meet both local realities and international dreams.
Strategic Moves for Investors: Navigating a 0.35 Timing Score
According to Rehani Soko property analytics, the current market timing score for premium Accra real estate stands at 0.35. While this figure might initially prompt caution, market data consistently shows that periods of contraction create distinct advantages for prepared buyers. The 20% dip in remittances has shifted the balance of power, transforming Accra into a buyer's market where negotiation is highly effective.
For the diaspora, the dream of owning a home in Ghana remains powerful. Securing a physical connection to your roots is a lasting achievement, and a clear process removes the uncertainty that often accompanies cross-border investments. Transaction patterns confirm that investors who shift their focus from immediate capital appreciation to steady, long-term rental income are navigating this phase successfully.
According to the Bank of Ghana (BoG), fluctuating exchange rates require careful financial planning, especially when converting foreign currency to Ghana Cedis (GHS). Investors must evaluate their financing structures carefully rather than rushing into purchases. Rehani Soko data shows that rental yields in mid-tier neighborhoods are stabilizing around 7.2%, providing a reliable income stream even as overall diaspora demand cools.
To capitalize on these conditions, buyers must act with precision. Whether you are looking to secure a family estate or an income-generating unit, you can explore available properties in Accra that fit this new economic reality. If you need clarity on structuring your purchase or evaluating specific neighborhood data, Ask Hani provides tailored insights to guide your investment journey. By aligning your strategy with current data, you can confidently secure your future in Ghana's evolving property landscape.
Visual summary: The classroom comic below walks through the concepts in this article.
📖
Page 1 of 2Hani Explains It
Actionable Next Steps
Ready to navigate the Accra property market? Use these resources to plan your next move:
- Explore Available Homes: properties in Accra
- View All Listings: browse all properties
- Understand Your Financing Options: mortgage calculator
- Request a Custom Rate: Get mortgage quote
- Get Expert Answers: Ask Hani
As Accra’s real estate market adapts to the 20% contraction in remittances, the dream of owning a piece of home remains very much alive for Ghanaians abroad. Connecting back to the homeland is a deeply personal journey, and having a clear process removes the uncertainty of navigating these shifting economic realities.
5 Key Takeaways
- According to Bank of Ghana (BoG) tracking, the 20% contraction in remittance flows has shifted diaspora buyer behavior from outright cash purchases to structured financing.
- Market data consistently shows developers across Accra are adjusting payment plans to accommodate staggered foreign incomes.
- Transaction patterns confirm a rising demand for mid-market apartments over sprawling luxury estates.
- Rehani Soko market intelligence indicates that despite the cash flow dip, long-term diaspora interest in Ghanaian real estate remains stable.
- Investors are increasingly relying on local mortgages to secure their assets while preserving their overseas liquidity.
Important Disclaimer
The information provided in this analysis is for educational and informational purposes only. It does not constitute financial, legal, or investment advice. Always consult with certified financial advisors and legal professionals before making property investment decisions in Ghana.
Frequently Asked Questions
- The timeline for securing a mortgage and closing on a property in Accra from overseas generally spans between eight to twelve weeks, depending on the complexity of the transaction and the responsiveness of all parties. According to Rehani Soko property analytics, the initial phase involves mortgage pre-approval, which requires submitting income verification, credit reports, and identification documents. Once pre-approved, the property valuation and legal due diligence take approximately three to four weeks. After the legal checks clear, the final mortgage offer is issued, and the transfer of funds is arranged. While the 20% remittance contraction has made some buyers more cautious, the actual administrative timeline remains steady. Working with specialized diaspora mortgage providers can streamline this journey, ensuring that your dream of owning a home in Ghana becomes a reality without unnecessary delays or administrative friction.